
Despite some challenges the IPMI market in France is focused on growth in a range of directions, Owain Thomas hears.
A well-developed economy and global population reach mean France is continuing to prove a strong international private medical insurance (IPMI) market.
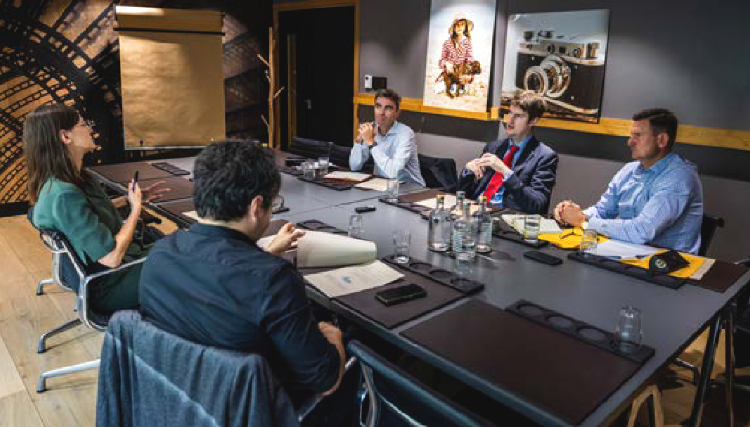
As the Health & Protection roundtable in association with Cigna Healthcare – Global Individual Health heard, prospects appear particularly bright for growth in a variety of areas, but as ever there are local factors at play.
One of the more unique elements of the France IPMI market is the impact of its domestic health provision where employers are obliged to offer top-up insurance to national social security.
This means that often the first query coming to an adviser from an employer looking for international coverage will be to provide this option to their staff in other countries.
However, this is often unrealistic for a variety of factors, meaning advisers have to introduce the concept of first euro insurance to clients.
Despite this speed bump in the process, advisers are confident with Verlingue head of multinational employee benefits Heike Fiedler very positive about the market she and her colleagues are working in at present.
“It’s a booming market and a dynamic market – as a broker or an insurer you have to be very reactive but it’s moving fast,” she said.
Fiedler noted that France was a very centralised country in terms of corporate demand with many big stock exchange-listed companies having headquarters in Paris.
This is added to by many international organisations that are also based in France, again typically in Paris.
“And last, but not least, it’s an interesting hub for the French-speaking African countries,” she added.
This upbeat approach was generally echoed by Aon France global benefits consulting lead and international mobility manager David Ginet.
“Yes, I’m pretty optimistic too and I think the market is growing,” he said.
“In France, we are lucky to have this range of very large corporates and large companies that can re-develop overseas.
“This is especially as in France, unfortunately, the economy and conditions are not very favourable, so these major companies are looking at growth outside of France, and so for that, because there is a lot of expertise they need to send people with expertise outside.
“And thanks to that we are focusing a lot on large corporates and this is pretty good news for us, so we are very optimistic about that.”
However, there are some concerns also bubbling up which need to be tackled affecting the wider international and mobility sector that the French market is not immune to.
“Nevertheless, we see some troubles; obviously political difficulties and uncertainty in some regions of the world,” Ginet continued.
“So the market might come down a bit as well because of that, but overall thanks to this ecosystem in France it’s positive for us.
“On the individual side, individuals really need coverage flexibility from insurers to find suitable solutions, and we need to address them a bit differently compared to before, but yes that’s pretty positive again.”
Booming individual market
From an insurer perspective the message was also highly positive.
Cigna Healthcare – Global Individual Health head of broker enablement and Europe sales Steve Martin explained how the insurer was seeing the individual market develop, particularly as customer profiles had changed.
“It’s a booming market for us,” he said. “When I started 25 years ago at another insurer we sold to expatriates who were on a very rich package, on assignment for three years, with schools paid for their kids, and tax-free salaries, and accommodation.
“That doesn’t happen much anymore; it still does, but not very often, so the range of customers we now work with is far more diverse.
“We’ve got the expatriates still, but now local nationals who are more understanding of international health insurance and want that, we also work with entrepreneurs.
“Furthermore, some younger people struggle to answer where are they actually from? ’Well, I don’t associate with one particular country anymore’, is a common reply from these groups.
“So globally mobile individuals and high-net-worth individuals are a key customer segment for us as well.
“More recently, we’ve noticed it’s not just individuals, but families as well; people going away with their families rather than just on solo assignments.”
Speaking of those global factors, Martin acknowledged the conflict in the Middle East which began earlier this year and has affected hubs in the area.
“We had many customers in Dubai who were expats living there, but rather than going home, they’ve just gone somewhere else,” he explained.
“So again there’s lots more portability and more people working more global in the market now than there ever used to be, because previous to that, they would have gone home.
“For us it’s a really booming market.”
Read and download the roundtable supplement by clicking the front page below or by following this link.
Steep budget cuts
However, for others the geopolitical situation is proving to be a real restraint on their clients and supporting their multinational activities.
Ambrelia customer relationship manager Kevin El Baz conducts the vast majority of his work within the non-governmental organisation (NGO) sector which has been hit hard by funding cuts.
“I won’t be so enthusiastic,” he noted.
“From what I’ve seen my NGO clients have a lot of trouble with budget. Since the Trump administration they’ve had budget cuts of around 40% or even 50% of what they used to receive for the last 10 years “The problem is that my clients don’t negotiate the premium, they negotiate the decision between cover and headcounts, so it matters a lot if I have to announce there’s a more than 20% increase in premium this year.”
Emphasising the effects this can have when trying to send people to dangerous locations such as Somalia or Gaza, El Baz explained if these organisations do not have the budget a lot of people will instead be staying at headquarters and will not be travelling and working anymore.
As a result, advisers must adapt and try to take other steps regarding the contract, premium, co-payment or digital services.
But ultimately the safety of staff takes priority.
“It’s quite difficult, because people tell me: ‘I won’t renew because I don’t have the money and I don’t want to send people to Africa or Gaza where it’s clearly dangerous, and I don’t want them to not be fully covered,’” El Baz continued.
“So that’s the problem, we have to be very diplomatic, we have to be very transparent regarding what they have as a coverage and what they don’t have.
“I hope it will be better in the next few years, but I’m really not sure.”
Strong growth prospects
Away from the highly distressed IGO sector, growth prospects from the French market appear strong in many regards.
Martin notes that outbound French nationals are a core element and one of the top ten largest populations under cover for the insurer.
“It’s really started to move forward for us; there are some political situations and the state of the world and certain countries where we’re seeing some people migrating overseas,” Martin said.
“But also highly educated, skilled, experienced French nationals are sought after by different countries around the world too, so we’re seeing a lot of those being hand-picked to go abroad, work and use their skills and education.”
In terms of locations, Asia is proving a particularly popular destination for Martin’s team, especially for those exiting the Middle East but choosing not to return home.
Perhaps surprisingly given reports from other regions, not least North America itself, the USA is also an increasingly common destination.
“America’s an interesting one for us, in fact we see quite a lot of French people going to the States,” Martin continued.
“That is one of the most popular travel corridors we have now for French nationals exiting France, but of course we have many partners in the US, and we are seeing US nationals leaving there as well.”
Europe is also strong for the insurer with local regulations and tax incentives playing their part.
For example, Italy’s flat tax rate regardless of earnings level and with no required investment is now drawing in globally mobile individuals while Portugal’s long-running tax incentives have become a well-established attraction.
Africa and Asia
Verlingue’s Fiedler has also seen some specific locations for inbound and outbound activity among her French clients.
“We have a few clients with quite a high number of Indian expats entering France where the situation is not always very clear,” she said.
“Sometimes you have to undo things to put them back in place in a more structured way.
“We also have French clients with offices or operations in French-speaking African countries, and for example, we have been asked to set up coverage for the top managers so they have coverage in France.
“They’re based in Africa, but in case they have a severe illness, they want to get treatment in a French city.
“However, Africa’s a bit difficult at present with Ebola, especially in Congo, where we had a few business opportunities, but insurers, for quite obvious reasons, were a bit reluctant. Of course, the language creates a link, it’s not an easy market, but there are definitely opportunities there.”
For Aon’s Ginet, Asia and especially dynamic cities such as Singapore are generating a lot of movement.
However, he notes there are a couple of distinct client markets open for attention.
“Middle-sized and growing companies would be a good one to tackle more,” he said.
“Sometimes they are a bit behind and they would like to now offer better coverage to their internationally mobile employees.
“Also start-ups and generally more employees would like to have experience outside of France, they want to be given experience elsewhere, so other types of mobility are in demand.
“If we can grab this opportunity, and provide collective policies for that type of population, it’s a good opportunity,” he concluded.
Read and download the roundtable supplement by clicking the front page below or by following this link.