Closing the global protection gap will require providers to think differently about how they engage with young people.
But providers will also need to design products specifically tailored to the needs of these younger generations or face an ever shrinking target marketplace.
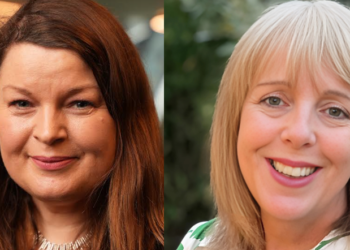
This is according to Samantha Chow, vice president, global life assurance and health leader at Capgemini (pictured), who sat down with Health & Protection during a whistlestop visit to London ahead of travelling to Bengaluru, India, yesterday.
Awareness and knowledge gaps
Last month, Capgemini’s World Life Insurance Report 2027 found nearly half (47%) of consumers are actively considering a purchase, but that this interest is not translating into sales.
In particular, awareness and knowledge gaps were stopping would-be life insurance customers from taking out cover.
Elaborating on the reasons for this lack of sales conversion, Chow maintained that while they are myriad, a key factor is that protection products have been around for a long time.
“People’s needs hundreds of years ago were quite different,” Chow explains. “It was about having to manage a family absence of a spouse or husband who was going to war, to a farm, out hunting, etc. So there was a purpose.
“There was a pool of money that said, ‘if something happens to me out in the field, you, the rest of my community, will take care of my family’.
“Today, if you think about the evolution of what we’ve gone through financially and the reason for life and protection insurance, we aren’t going into the fields and hunting anymore.”
Lack of urgency
According to Chow, the need to leave a legacy is not there anymore – particularly among younger generations.
“There isn’t an urgency that says, ‘I need to leave a legacy behind’, or ‘I need to leave something behind to cover income or protect my income in the future if I was to have a serious injury or pass’ or what have you,” she continues.
“So, fast forward even a little bit further to this younger generation we have today, they look at life insurance and protection insurance as almost a waste of money because it’s a case of use it or lose it.
“And even in life insurance, it’s death insurance. I will never see my money.”
Different life stages
Chow explains that younger generations also may never go through the same life stages expected of their parents and grandparents.
“Because they’re not getting married,” she continues. “They’re not having children. They don’t buy their homes. They’re renting. They don’t own cars and if they do, they’re paying them off rapidly, so they don’t carry debt or things that income protection might help them with.
“They’re balancing spend in areas like their Netflix account or they’re just putting it in savings.”
Lack of engagement
Even where they do buy into taking out cover, Chow also points to a lack of engagement throughout the process of purchasing a life insurance or protection policy.
“It’s set it and forget it,” she continues.
“Even when you talk about group protection, when you’re in the employer space, the only conversation or interaction they have with those policies is during open enrolment time, and they don’t understand the products or how to use them in today’s world.
“So as a result, they’re not getting the sales because their products are no longer relevant to these individuals.”
Better marketing
In terms of what can be done to more effectively engage younger generations, Chow suggests better marketing of products.
“It’s marketing the features of those products around behaviours so they are very personalised to someone’s life stage where they are, and how they utilise these products throughout their lifetime,” Chow continues.
“It’s marketing and sharing the living benefits that live within the actual products that can be used over the course of time.
“There’s a lot of misunderstanding about how these products can be used. They just think of them as income protection or death insurance and by marketing better, creating more clear short-form content will help them digest and understand better the products that they have to offer.”
Broker training
But Chow also contends that the way products are sold also needs to change, with more of an emphasis on the training of brokers.
“Training those agents and advisers to sell more behaviourally, again, very personalised to life stage which can again create a better relationship and ongoing sale,” she continues.
“Getting them past the ‘it’s not relevant to me stage’ and converting them into the sale.”
Fitting today’s target market
And finally, Chow calls for products that fit today’s evolving target market.
“Because what we’re seeing in the future is as the silent generation and the boomers expire, you might see a growth in high net worth by dollar, but a shrink in the number of people in the target market and even in that middle to lower market, there is just going to be a shrink in people,” she adds.
“So the target market itself is shrinking if we don’t overcome products that fit the next generations, then they’re already at a loss in trying to overcome the protection gap.”