
Insurers, advisers and other key partners in the protection insurance sector have been urged to strongly consider and act to avoid products being used for economic abuse.
They have also been pressed to speed-up providing joint-protection products which can be split into separate policies when economic abuse is discovered.
The messages came following the release of the Association of British Insurers’ (ABI) guidance on preventing, reducing and managing economic abuse.
The guidance did not specifically call on insurers to separate joint policies if they are being weaponised against a member, and has generally been welcomed among those Health & Protection spoke to.
But while an ABI group is exploring the situation the sector has been implored to act faster.
Indeed, one in six women in the UK has suffered economic abuse from a partner, according to Surviving Economic Abuse (SEA).
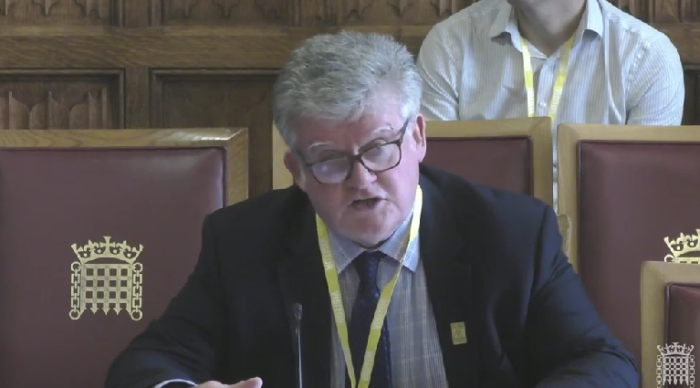
Johnny Timpson, Financial Services Consumer Panel member and ambassador for the insurance industry and profession at SEA, (pictured) is already working on developing more effective joint-life policy splitting clauses with Professor James Davey of the University of Bristol Law School.
“What we need to do, first and foremost, is come up with brand new policies,” he told Health & Protection.
“It makes absolute sense for those policies to be written as two single life policies rather than joint.”
Time for an upgrade
Although Timpson accepts there are instances where a joint-life policy may be appropriate, he said it was important the distributor checks for signs of economic abuse.
He is also developing an effective splitting clause for older policies. And those that already have such a mechanism need an upgrade as they require consent from both parties to split the policy.
“That’s the problem,” Timpson said.
“The party who is trying to use the policy for abuse purposes is not going to give that permission.”
He points to The Exeter as an example of an insurer that has been innovative in this area.
The insurer has introduced joint-life cover which can be converted into two single policies if one of the policyholders asks for it.
For such a split clause to be widely adopted, the industry will probably have to take a risk-based approach for it to work.
“If we think financial control is a factor, we are just going to take a risk and split the policy or allow its cancellation,” Timpson said.
“Those are subject to ongoing discussion,” he added. “We’ve got an ABI working group that is discussing these things.”
Practical implementation
Timpson was involved in the ABI’s guidance – A guide to supporting customers experiencing economic abuse – through his role in advising SEA, a charity which worked on the guide.
For Timpson, it is now vital for the industry to focus on the practical implementation of the guidance.
The main recommendations included reviewing the consent, disclosure and correspondence requirements to avoid someone taking control of a joint policy to abuse their partner.
Other pointers included providing an exit route from digital or standard joint policies and setting controls to ensure that payouts cannot be diverted away from a beneficiary.
A matter of life and death
Ruth Gilbert, partner at Insuring Change, urged the whole sector to step back and take a wider view at everything they do to successfully address the potential for abuse.
“This ABI guide shines a light on the many ways in which insurance, and protection in particular, can be misused to become an instrument of delivering the opposite of peace of mind it is intended for,“ she said.
“When it comes to protection, it is literally a matter of life and death for some victims of abuse.”
Gilbert added that insurers and advisers need to question the advice, processes and product design to reduce risk of economic abuse.
For example, could this allow an abuser to find a victim’s new address or the details to access their policy?
Could it allow them to fraudulently take out life cover on a victim, refuse to separate joint-life cover and receive all or part of the benefit payable for the victim’s critical illness?
In short, she added, could they use their status as a trustee of a policy to control a victim’s life?
Complex and highly individual
Rebecca Ward, head of health and protection policy at the ABI, told Health & Protection that economic abuse can have “devastating” effects on people’s lives.
“It doesn’t come in a specific shape or form – it’s often complex and highly individual,” she said.
Ward noted that due to the variety of products and business structures across the industry, there was no one-size-fits-all solution to the problem.
“This is why the guide encourages firms to assess each situation individually, prioritise customer safety, apply flexibility and tailor support to victim-survivors’ needs, while identifying and closing loopholes that perpetrators can exploit,” she added.
Striking a balance
But do the recommendations go far enough, especially as the ABI did not call on joint-protection policies to be banned altogether?
The guidance does an “excellent job” of raising awareness and helping insurers identify risks, support customers and reduce opportunities for abuse to occur, said Jack Southcott, head of proposition (protection) at The Exeter.
“The guidance strikes a good balance between providing practical direction and allowing firms flexibility to implement appropriate solutions.
“I hope it acts as a springboard to further collaboration between insurers, regulators and specialist charities,” Southcott added.
Turning awareness into action
Jennifer Gilchrist, senior industry affairs manager at Swiss Re, called the recommendations “practical, proportionate and give firms a clear framework for turning awareness into action”.
She welcomed the focus on staff training, safe communications and disclosure, product design and learning from the lived experience of victim-survivors.
“Products designed to provide security can, unfortunately, be used as tools of control,“ she said.
“That means we need to think about economic abuse at the outset when products and processes are designed or redesigned and throughout the customer journey, before and after a purchase.
“It is particularly important to consider where standard processes, such as joint arrangements, consent requirements or communications, could inadvertently create additional risk.
“Getting that right can help make a very real difference to someone’s safety, financial independence and ability to move forward.
“The next important step will be seeing the guidance embedded in practice, with firms sharing what works, continuing to listen to victim-survivors and developing evidence of good outcomes being achieved.
“As our understanding continues to develop, that shared learning can help the industry to keep strengthening its approach,” she added.